Free FIRE calculator

Net Worth View

Data

Your data

Changes save automatically in this browser.

Complete backup

JSON

All your records and settings in one file you can restore later.

Spreadsheets

CSV

Balances and cash flow only. Importing adds records to your data.

Explore your path to financial independence

Explore when you could reach your financial independence target. Model contributions, inflation, pension access and retirement withdrawals, then export your FIRE projection chart. Results illustrate your assumptions, not a guaranteed retirement date.

  • Free, no sign up
  • No account required
  • No bank connection required
  • Your financial data stays on your device
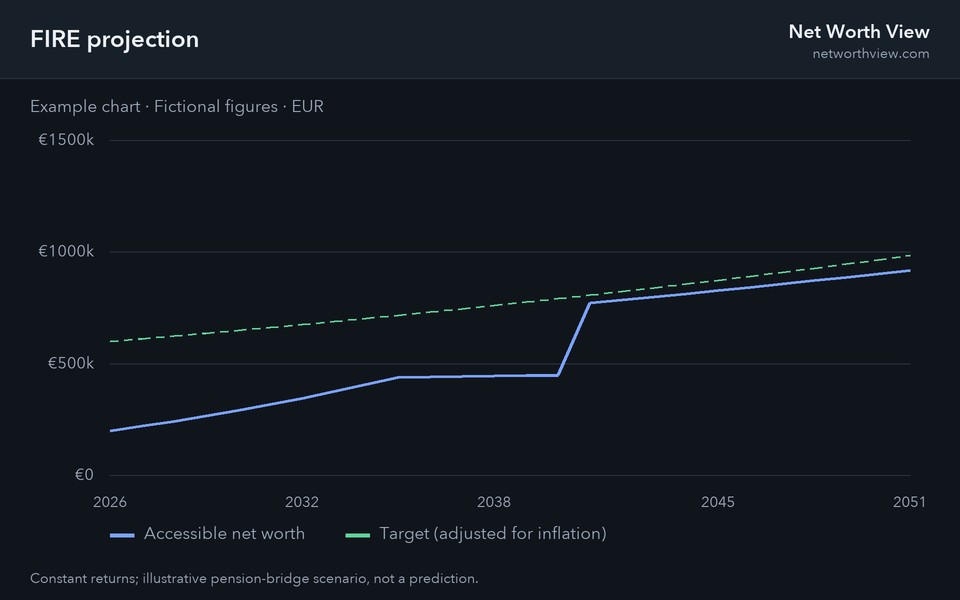
Example FIRE projection chart showing accessible net worth and an inflation-adjusted target in euros
Example chart · Fictional figures

Explore a retirement scenario

Explore when you could reach your financial independence target with a free FIRE calculator and retirement projection. Model contributions, inflation, pension access and withdrawals, and export your charts to share. No account or bank connection is required; your financial data stays on your device.

FIRE means financial independence, retire early. This calculator projects your latest net-worth snapshot using the assumptions you choose. Cash, investments, property and pensions can each have a different constant annual growth rate.

Enter planned monthly or yearly additions and debt repayments, or explicitly apply a contribution suggested from cash-flow savings. The inflation option increases additions and drawdown with the selected inflation rate, rather than modelling salary growth separately.

The calculator reports the first year the selected net-worth scope reaches your target. Property can count toward projected net worth and the target when included, but it is never a source of retirement withdrawals, and reaching the target does not establish that retirement spending is sustainable.

Drawdown uses cash, investments and any accessible pension. Review both balances and withdrawal shortfalls. These are deterministic scenarios with constant rates, not predictions: they do not model market volatility, sequence-of-returns risk, taxes or fees.
How to build a FIRE projection

  1. Record at least one net worth snapshot. The projection starts from your latest balances, so bring them up to date before relying on a result.
  2. Replace the default growth rates, inflation rate and projection length with assumptions that fit your own situation.
  3. Add a monthly or yearly contribution for each asset class, with an end year if it stops, and a repayment for any debt.
  4. Set a target, a drawdown rate and a start year, then use the chart and yearly table to see when the target is met and how accessible assets hold up once withdrawals begin.

Projection settings explained

Target basis
Nominal is a fixed future amount. Real (today’s money) keeps purchasing power constant, so the nominal sum needed rises each year with inflation.
Pension access year
The first year a pension counts as accessible. Until then it keeps growing but is left out of target progress and drawdown. Leave it blank to count the pension from the start.
Contribution end year
The last year an asset class receives its addition. It is set separately from the drawdown start, so contributions can continue after withdrawals begin.
Drawdown rate
The first withdrawal as a percentage of accessible cash, investments and pension. With inflation adjustment on, later withdrawals rise with inflation.
Re-base drawdown at pension access
Recalculates the annual withdrawal from the whole liquid portfolio in the year a pension unlocks, instead of keeping the earlier amount.